


Artificial intelligence (AI) has become the defining investment narrative of this cycle. With surging capital spending and expanding valuations, investor conviction — particularly around dominant U.S. large‑cap technology companies — has hardened.
But have investors gotten ahead of themselves?
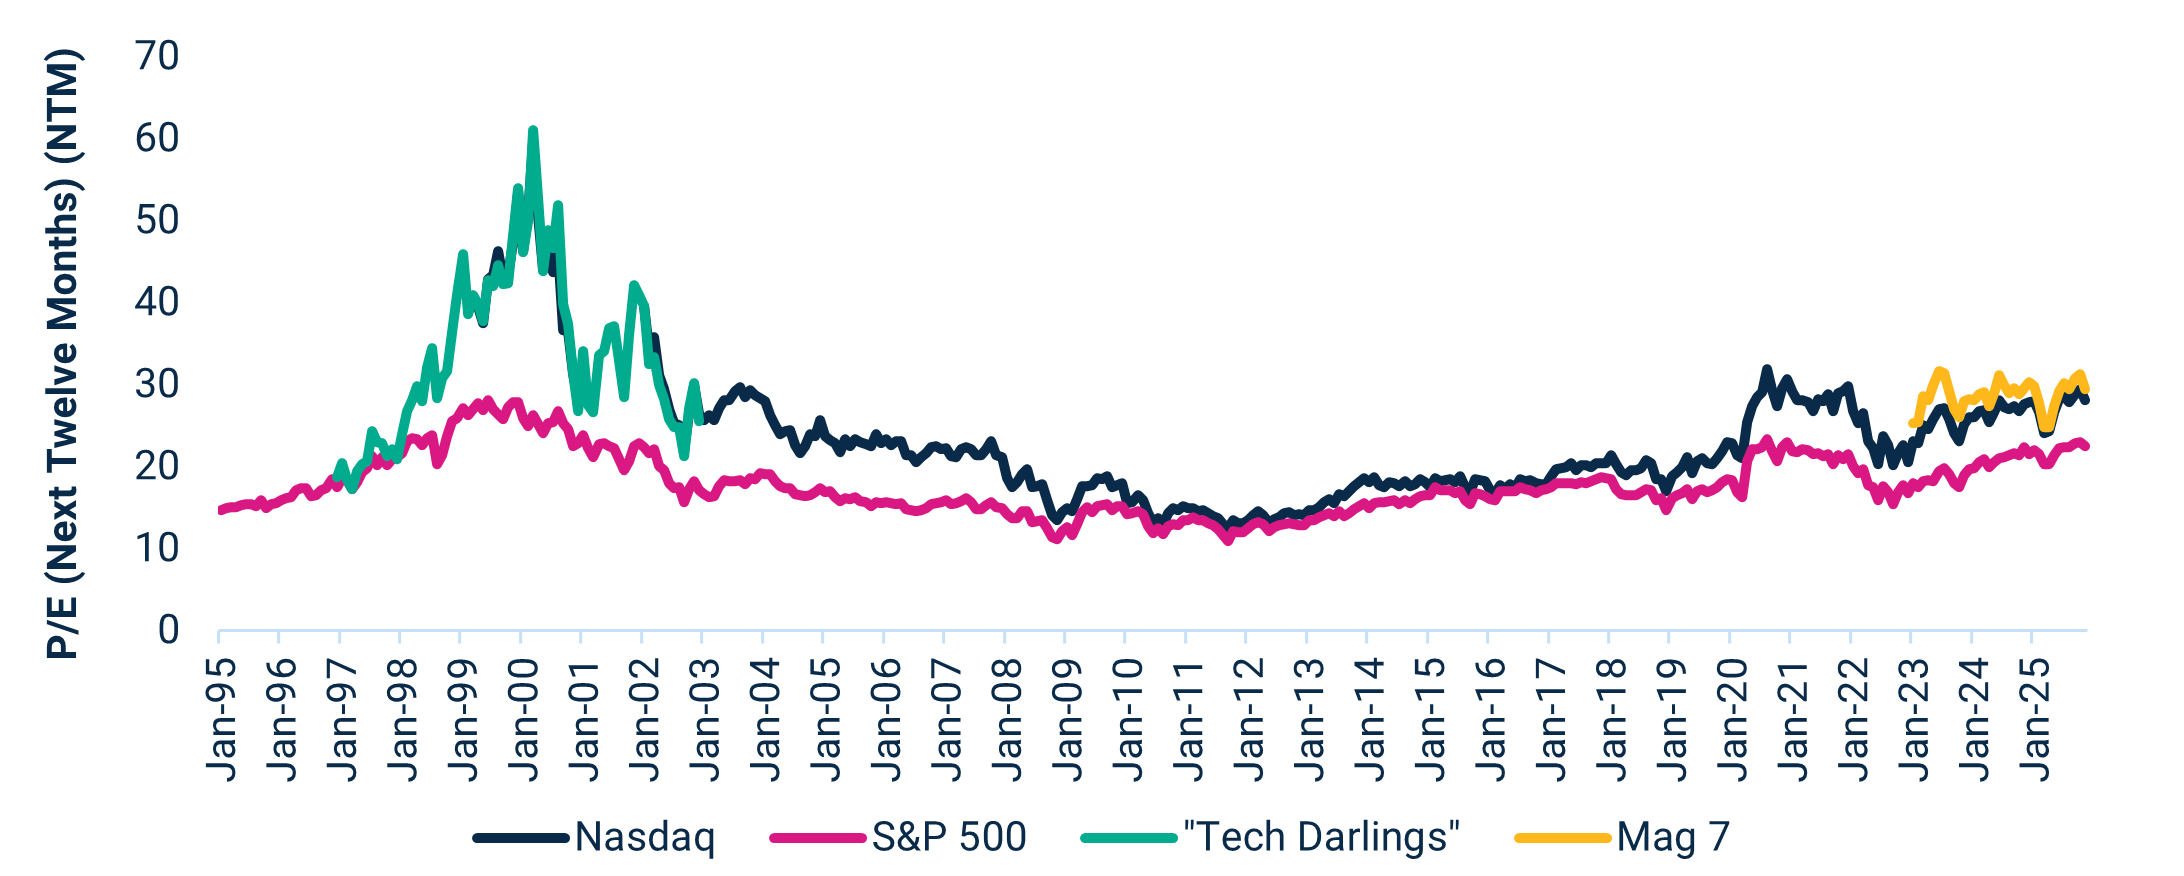
Compared to the late 90s, today’s dominant AI‑linked companies trade at lower multiples than speculative tech did during the dot‑com era.
Valuations: The Tech Bubble vs. Today
Source: Harbor Capital Advisors, FactSet. Data as of 11/30/2025. The performance quoted represents past performance which is no guarantee of future results.
“Tech Darlings” include Amazon.com, Inc., Cisco Systems, Inc., Dell Computer Corp., eToys, Inc., Intel Corp., Lucent Technologies Inc., Microsoft Corp., Nortel Networks Corp., Oracle Corp., Qualcomm Inc., Sun Microsystems Inc., theglobe.com, Inc., JDS Uniphase Corp. TMT includes Communications Equipment, Telecom, Software, TMT Services, Media, Tech Hardware, Electronic Equipment, Semiconductors.
In this cycle, capital is flowing toward businesses with scale, balance sheet flexibility, and visible demand — not unproven concepts. Valuations may be full, but they are not detached from earnings power.
As a result, we find that the pendulum has swung toward enthusiasm, but not yet toward irrationality — at least not where fundamentals remain strong. That said, the easy phase of the AI trade (where exposure alone was rewarded) is giving way to a more demanding environment.
The shift that matters
In our view, the next phase of the AI cycle is unlikely to reward exposure alone. Leadership is already beginning to diverge based on who can convert infrastructure spend into revenue growth and margin durability.
To that end, we expect 2026 could mark a transition from AI infrastructure beneficiaries to AI adoption beneficiaries. Companies that use AI to drive productivity and operating leverage should increasingly differentiate themselves.
Implications for Allocators
Put simply – we believe this is not a year for binary AI bets. In our view, allocators should consider the likelihood of:
- Greater dispersion between AI winners and losers
- Increased scrutiny on returns, not narratives
- Continued leadership from dominant, U.S. large cap platforms – without broad, indiscriminate upside
Portfolios built on the assumption that AI exposure alone is sufficient risk disappointment. We believe selectivity, balance sheet strength, and demonstrable economics will matter more as the cycle matures.
We think AI’s moment in 2026 is less about mania — and more about discernment, requiring careful consideration for allocators.
To learn more about Harbor’s analysis of the market environment as a whole and opportunities for prudent asset allocation, check out our weekly research presentation – The Current.
Important Information
Investing entails risks and there can be no assurance that any investment will achieve profits or avoid incurring losses. Stock markets are volatile and equity values can decline significantly in response to adverse issuer, political, regulatory, market and economic conditions.
The views expressed herein may not be reflective of current opinions, are subject to change without prior notice, and should not be considered investment advice or a recommendation to purchase a particular security.
The price-to-earnings (P/E) ratio measures a company's share price relative to its earnings per share (EPS).
The S&P 500 Index is an unmanaged index generally representative of the U.S. market for large capitalization equities. This unmanaged index does not reflect fees and expenses and is not available for direct investment.
The Nasdaq Composite Index, which includes over 2,500 stocks, is a key indicator of the tech sector's performance and the overall market sentiment.
The Magnificent 7 (or Mag 7) stocks are a group of seven high‑performing and influential U.S. companies in the technology sector, including Alphabet, Amazon, Apple, Tesla, Meta Platforms, Microsoft and Nvidia.
Copyright ©2026 Harbor Capital Advisors, Inc. All rights reserved.